
gilbsy123
How to Pitch Private Money Lenders and Get Funded Every Time
If you want to know how to pitch private money lenders in a way that gets funded consistently, you need a simple structure, a confident delivery, and a clear value proposition. Most investors overcomplicate the pitch, but private lenders only care about a few specific things — and when you hit those points cleanly, funding becomes predictable.
The Mindset Shift That Changes Everything
Stop thinking “I need money.” Start thinking “I’m offering an investment opportunity.” Private money lenders want to earn better returns. You’re not begging—you’re bringing them a deal secured by real estate at 8–10% returns. That’s valuable.
Who Should You Pitch First?
Start with warm prospects: people who already know and trust you. Friends, family, business associates, former colleagues, your dentist, doctor, accountant. People who complain about low CD rates or volatile stock markets are perfect candidates.
Build Your Credibility Package Before You Pitch
Before any conversation, prepare:
- A one-page investor overview about you (bio, investing philosophy, track record)
- A sample deal analysis (real deal with real numbers)
- A clear FAQ document about how private lending works
- References from past deals (or a mentor/partner if you’re new)
The Pitch Conversation Framework
- Step 1 – Build the relationship (don’t pitch yet)
- Step 2 – Plant the seed: “I’ve been doing real estate deals. I work with private investors who earn 8–10% secured by property. Would you ever be open to hearing more?”
- Step 3 – If yes: schedule a dedicated 30-minute conversation
- Step 4 – At the meeting: walk through how private lending works, how you protect lenders, and your track record
- Step 5 – Present the specific deal: purchase price, renovation plan, ARV, their return, their security position
- Step 6 – Answer questions, overcome objections confidently
- Step 7 – Ask for the commitment
Common Objections and How to Handle Them
“What if you can’t pay me back?” → Explain the collateral: “The property is worth $X and we’re only borrowing $Y. Even if I disappeared, the property secures your investment.”
“I don’t know anything about real estate.” → “You don’t have to. That’s my job. Your job is to fund the deal and collect interest.”
“What if the market crashes?” → “We only lend at 65–70% of current value, so there’s a 30–35% cushion before you’d lose a dollar.”
What to Send After the Meeting
- A follow-up email with a one-page deal summary
- The promissory note and deed of trust templates (reviewed by an attorney)
- Your credibility package and any additional deal analysis
How to Handle Your First Deal with a New Lender
Over-communicate. Send weekly updates. If there’s an issue, tell them before they ask. Deliver on every promise. The first deal is an audition—nail it and you’ll have a lender for life.
Now that you know how to pitch, learn how to structure a private money deal and review private money lending legal requirements to make sure every deal is airtight.
Private Money Lending for Fix and Flip Investors: The Complete Guide
F ix-and-flip investing and private money lending were made for each other. The speed and flexibility of private money aligns perfectly with the fast-moving, time-sensitive nature of house flipping. Here’s everything you need to know.
Why Fix-and-Flip Investors Use Private Money
Banks won’t lend on distressed properties. Bank loans take 30–60 days to close. And banks certainly won’t fund renovation costs. Private money solves all three problems: it funds the purchase, covers part of the rehab, and closes in days not weeks.
The Typical Fix-and-Flip Loan Structure
Most private lenders fund fix-and-flip deals using one of two approaches:
Option A: Purchase + Rehab Hold-Back
- Lender funds 100% of the purchase price (up to 70% LTV)
- Renovation funds are held in reserve and released in draws as work is completed
- Borrower submits draw requests with photos and receipts
Option B: Purchase Only (Borrower Self-Funds Rehab)
- Lender funds only the purchase (lower LTV, lower rate)
- Borrower uses their own cash for renovations
- Lower cost but requires more capital reserves
Running the Numbers: Fix-and-Flip Deal Example
- Property: $100,000 purchase price
- Renovation Budget: $30,000
- ARV: $185,000
- Private Money Loan: $100,000 at 10% for 9 months
- Points: 2 ($2,000)
- Monthly Interest: $833
- Total Carrying Cost: $7,497
- Sale Price: $185,000
- Profit After All Costs: ~$35,000+
What Lenders Look at in Fix-and-Flip Deals
- Purchase price vs. ARV (looking for 70% rule or better)
- Detailed, itemized renovation budget
- Your exit strategy (list date, listing agent, target sale price)
- Your track record on previous flips
- The local comparable sales (comps) supporting the ARV
Rehab Draw Schedules: How They Work
When lenders include rehab funds, they’re released in stages:
- Draw 1: 25% of rehab budget (foundation, framing complete)
- Draw 2: 50% completion (rough plumbing, electrical done)
- Draw 3: 75% completion (drywall, HVAC complete)
- Final Draw: Property 100% complete and ready for sale
Each draw requires an inspection or photo documentation.
Common Mistakes Fix-and-Flip Investors Make
- Over-estimating ARV (be conservative)
- Under-estimating renovation costs (add 15–20% buffer)
- Not having an exit strategy before borrowing
- Choosing a lender based on rate alone (relationship and reliability matter)
- Missing the draw schedule documentation requirements
Finding Private Money for Your First Flip
Start with your personal network, local REI meetups, and BiggerPockets. Bring a deal package showing your purchase price, renovation plan, comparable sales, and projected profit. Even without a track record, a compelling deal can get funded.
Get the full foundation: private money lending basics, how to find private money lenders, and how to pitch private money lenders.
Private Money Lending vs. Hard Money Loans: What’s the Real Difference?
 Two of the most common non-bank financing options in real estate—private money lending and hard money loans—are often used interchangeably. But they’re not the same. Knowing the difference can save you thousands and help you choose the right tool for each deal.
What Is Private Money Lending?
Private money comes from individuals—friends, family, fellow investors, or high-net-worth individuals—who lend their personal capital for real estate deals. The relationship is personal, the terms are negotiable, and there’s no institutional infrastructure behind it.
What Are Hard Money Loans?
Hard money loans come from companies (hard money lenders) that operate as semi-institutional lenders. They have standardized loan programs, underwriting criteria, and dedicated staff. They’re still asset-based, but less flexible than a true private lender.
Key Differences at a Glance
- Source: Individual vs. Company
- Rates: 8–10% private vs. 10–14% hard money
- Speed: Both fast, but private can be faster
- Flexibility: Private wins—terms are fully negotiable
- Relationship: Private is relationship-based; hard money is transactional
- Volume: Hard money lenders can fund multiple deals at once
- Fees: Hard money usually charges more points
When to Use Private Money
Use private money when you have an existing relationship with a lender, need maximum flexibility on terms, are working with an unusual property type, or want to avoid heavy fees.
When to Use Hard Money
Use hard money when you don’t have a private lender lined up, need a lender who can fund multiple deals, or want a structured program with clear guidelines.
Which Is Better for Beginners?
For beginners without existing relationships, hard money is often the entry point. As you build your track record and network, transitioning to private money reduces costs and increases flexibility.
The Bottom Line
Both are powerful tools. The best investors use both strategically. Start with hard money to build your track record, then cultivate private money relationships for lower rates and better terms.
Want to dive deeper? Read our post on what is private money lending and how to find private money lenders to build your strategy.
Private Money Lending Rates: What to Expect in 2026
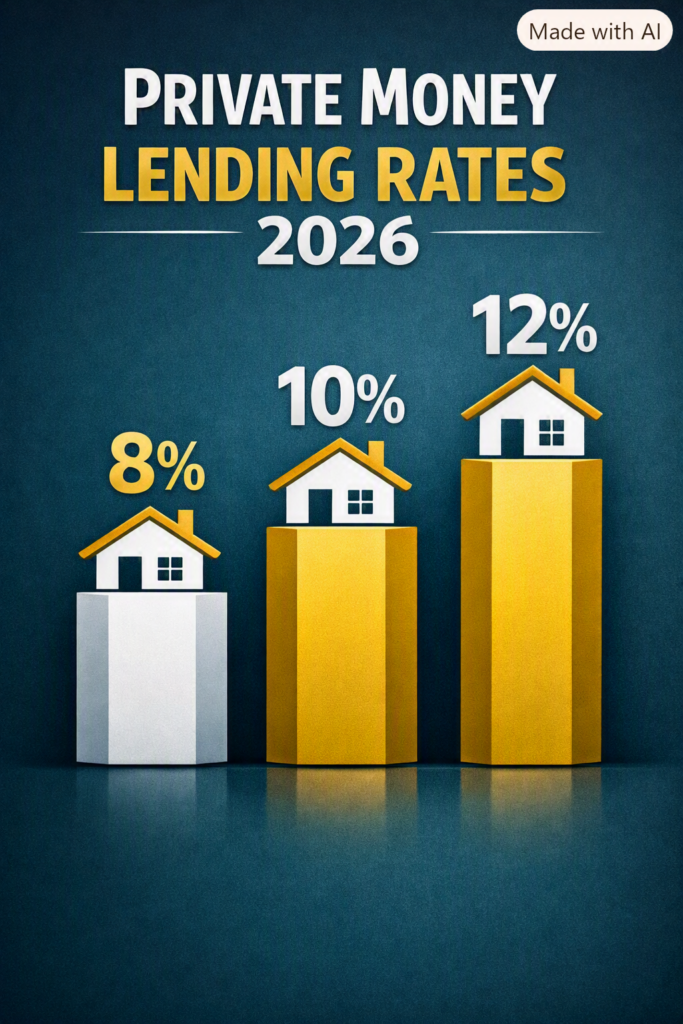 One of the first questions real estate investors ask about private money is: “How much does it cost?” Understanding private money lending rates helps you accurately analyze deals and negotiate better terms. Here’s a complete breakdown.
What Are Typical Private Money Lending Rates?
In 2026, private money lending rates typically range from 8% to 13% annually, depending on:
- The lender’s risk tolerance and relationship with the borrower
- The property type and condition
- The loan-to-value ratio (LTV)
- The loan term and exit strategy
- The borrower’s track record
Interest Rate Breakdown by Property Type
- Fix-and-Flip (residential): 9–12%
- BRRRR Rentals: 9–11%
- Commercial Bridge: 10–13%
- Land Loans: 10–14%
- New Construction: 10–13%
What Are “Points” in Private Lending?
Points are origination fees charged upfront. One point = 1% of the loan amount. Private lenders typically charge 1–3 points. On a $200,000 loan at 2 points, you’d pay $4,000 at closing.
How LTV Affects Your Rate
The lower your LTV, the lower your rate. A 60% LTV loan carries less risk than an 80% LTV loan—lenders reward less risk with lower rates. Most private lenders cap LTV at 70–75%.
How Borrower Track Record Affects Rate
First-time borrowers typically pay higher rates (10–12%). Repeat borrowers with a proven track record often negotiate down to 8–9%. Your credibility has real monetary value.
Comparing Private Money to Hard Money
Hard money lenders typically charge 11–14% with 2–4 points. Private individual lenders often charge 8–10% with 1–2 points. Over a 12-month, $200,000 loan, that difference is $6,000–$8,000 in savings.
How to Negotiate Better Rates
- Bring a strong deal with conservative numbers
- Show your track record and references
- Offer a lower LTV (more equity cushion for the lender)
- Offer a personal guarantee
- Start with one solid deal and build the relationship
Are Private Money Rates Worth It?
Yes—when the deal math works. If you’re buying a property at $0.70 on the dollar with strong ARV, the 10% interest rate is a cost of doing business, not a dealbreaker.
Want to learn how to structure a deal around these rates? Read how to structure a private money lending deal and how to analyze a fix-and-flip deal.
How to Structure a Private Money Lending Deal (With Examples)
 Private money lending offers flexibility; however, it requires careful due diligence. Whether you’re an investor looking to grow your portfolio or someone exploring passive income opportunities, understanding how private lending works can help you create steady returns while supporting other investors’ projects.
The Three Core Components of Any Private Money Deal
- Loan Amount: How much is being borrowed
- Interest Rate & Points: The cost of the capital
- Repayment Structure: How and when the loan is repaid
Structure #1: Interest-Only with Balloon Payment (Most Common)
The borrower pays monthly interest only, with the full principal due at loan maturity (typically at sale or refinance).
Example: $150,000 loan at 10% for 12 months
- Monthly payment: $1,250/month
- Total interest paid: $15,000
- Balloon at maturity: $150,000
Best for: Fix-and-flip investors who need cash flow during renovation.
Structure #2: Deferred Interest (Accrued)
No monthly payments. Interest accrues and is paid along with principal at maturity.
Example: $150,000 at 10% for 6 months
- Total interest accrued: $7,500
- Total repayment at maturity: $157,500
Best for: Investors who want zero carrying costs during rehab.
Structure #3: Equity Participation
Lender receives a percentage of the profit instead of (or in addition to) interest.
Example: Lender funds $150,000 at 0% interest but receives 25% of net profit.
- Net profit on deal: $60,000
- Lender’s share: $15,000
Best for: High-upside deals where the borrower wants to reduce cash outlay.
Essential Legal Documents
Every private money deal needs:
- Promissory Note: The borrower’s written promise to repay
- Deed of Trust or Mortgage: Records the lien against the property
- Loan Agreement: Detailed terms and conditions
- Personal Guarantee (optional): Borrower’s personal liability
- Title Insurance: Protects lender’s lien position
First Position vs. Second Position Loans
First position lenders are paid first if the property is foreclosed. Second position lenders get paid only after first position is satisfied. Always understand your lien position—first position is standard for private money.
How to Protect Yourself as a Lender
- Never lend more than 70–75% LTV
- Get title insurance
- Record your deed of trust immediately
- Require hazard insurance on the property
- Have an attorney prepare all documents
Private money lending offers investors a way to earn consistent returns while helping others fund real estate deals. By understanding the process, setting clear terms, and protecting your capital, you can build a reliable income stream and long-term relationships in the real estate community. Start small, stay informed, and let private money lending become a cornerstone of your financial growth.
Get the full picture by reading private money lending rates, how to become a private money lender, and the legal requirements for private money lending.
How to Become a Private Money Lender: Step-by-Step Guide
Build Wealth Safely Through Private Lending
If you have capital sitting in savings accounts earning 1–2%, private money lending offers a compelling alternative: secured, collateralized returns of 8–12% backed by real estate. Moreover, private lending gives you predictable returns. In fact, most new lenders start with small, safe deals. Here’s how to get started.
Step 1: Understand What You’re Getting Into
As a private lender, you’re not buying property—you’re making a loan secured by property. Your return is fixed (interest). Your risk is the property value dropping below your loan balance. You don’t share in the upside, but you’re protected by the collateral.
Step 2: Define Your Lending Parameters
Before lending a single dollar, decide:
- Minimum/maximum loan size you’re comfortable with
- Property types (residential, commercial, land)
- Geographic area (local only, or national?)
- Maximum LTV you’ll accept (most lenders cap at 70–75%)
- Loan term (6 months, 12 months, 24 months?)
- Minimum interest rate you require
Step 3: Find Borrowers to Lend To
Connect with active real estate investors through local REI clubs, BiggerPockets, your personal network, and real estate attorneys. Vet borrowers by reviewing their track record, deal analysis, and references.
Step 4: Evaluate Every Deal Carefully
The property is your collateral—so evaluate it rigorously:
- Get an independent appraisal or BPO (Broker Price Opinion)
- Review the borrower’s renovation budget and timeline
- Confirm the exit strategy is realistic
- Never lend more than 70% of the as-is value (or 65% of ARV)
Step 5: Structure the Loan Legally
Always use a real estate attorney to prepare:
- Promissory note (the loan agreement)
- Deed of trust or mortgage (the lien on the property)
- Personal guarantee (optional but recommended for new borrowers)
- Title insurance (to protect your lien position)
Step 6: Fund the Deal and Collect Payments
Funds are typically wired to the title company at closing. Set up a clear payment schedule. Most loans are interest-only monthly with a balloon payment at maturity.
Step 7: Manage Your Portfolio
Track each loan: balance, payment history, maturity date. Have a process for what happens if a borrower misses a payment or defaults. Know your foreclosure rights in your state.
Tax Considerations
Interest income is taxable. If lending through a self-directed IRA, it may be tax-deferred or tax-free. Consult a CPA familiar with real estate lending.
Ready to lend?
Start by reviewing private money lending rates and understanding the legal requirements of private money lending.
How to Find Private Money Lenders for Real Estate Investing
The Smartest Ways to Connect With Private Money Lenders
One of the most common questions new investors ask is: “Where do I find private money lenders?” The answer might surprise you—they’re closer than you think. Here’s a proven roadmap.
Start With Your Existing Network
Your first private lenders are often people who already know, like, and trust you. Consider: family members with savings, business colleagues with disposable capital, friends who complain about low CD or savings rates, former colleagues, and your dentist, doctor, or accountant.
You’re not asking for a gift—you’re offering them a secured, collateralized investment at 8–10% returns. That’s a compelling offer.
Real Estate Investor Meetups (REI Clubs)
Local REI meetups are goldmines for private money connections. Attend consistently. Share your deals. As people see you executing, they’ll naturally ask about investing with you. Find local meetups at Meetup.com, BiggerPockets Events, or your local REIA (Real Estate Investors Association).
Online Platforms
Several platforms connect borrowers with private lenders:
- BiggerPockets forums and marketplace
- Connected Investors platform
- PeerStreet (institutional private lending)
- Groundfloor (retail lender marketplace)
- LinkedIn (search “private lender real estate”)
Build a Credibility Package First
Before approaching any lender, have a professional credibility package ready:
- Your investing bio and track record
- Sample deal analysis (with real comps)
- References from past deals
- A clear explanation of how the loan is structured and secured
Real Estate Attorneys and Title Companies
Attorneys who handle real estate closings know who has capital. Title companies see who funds deals repeatedly. Build relationships with these professionals—they can refer you to lenders who are actively looking for deals.
Self-Directed IRA Holders
Millions of Americans have self-directed IRAs that can legally invest in real estate loans. These individuals are actively looking for higher returns than the stock market offers. Connect with custodians like Equity Trust or STRATA Trust Company.
The Art of the Ask
When approaching a potential lender, never lead with “I need money.” Lead with: “I found a great deal and I’m building my investor network. Would you be open to a conversation about how I structure deals?” Educate first, ask second.
CTA: Once you find a lender, you’ll need to know how to structure a private money deal and how to pitch private money lenders. We’ve got both covered.
What Is Private Money Lending? A Complete Beginner’s Guide
 If you’ve ever heard the term “private money lending” and wondered what it actually means—you’re in the right place. Whether you’re a real estate investor looking for flexible financing or someone with capital looking to earn better returns, understanding private money lending basics is the first step.
What Is Private Money Lending?
Private money lending is when an individual (not a bank or credit union) loans money to a real estate investor, secured by the property itself. Unlike traditional bank loans, private money loans are funded by private individuals—often other investors, high-net-worth individuals, or those using self-directed IRAs.
The loan is typically secured by a deed of trust or mortgage on the property, giving the lender a legal claim to the asset if the borrower defaults.
How Does Private Money Lending Work?
The process is simpler than you might think:
- A borrower (investor) identifies a property deal.
- They approach a private lender with a deal package.
- The lender evaluates the deal—primarily based on the property value and exit strategy.
- Terms are negotiated: interest rate, loan term, points, and repayment structure.
- Both parties sign a promissory note and deed of trust.
- Funds are wired, the deal closes, and the lender earns interest.
Who Uses Private Money Lending?
- Fix-and-flip investors who need fast funding
- BRRRR investors building rental portfolios
- Real estate wholesalers who double-close deals
- New investors who can’t qualify for bank loans
- Experienced investors who need to close quickly
Private Money vs. Hard Money vs. Conventional Loans
Private money lenders are typically individuals with capital. Hard money lenders are companies that operate similarly but at scale. Conventional loans come from banks and require strict qualification. Private money sits between personal relationships and institutional lending—offering flexibility, speed, and negotiable terms.
Why Private Money Lending Matters
Speed and flexibility are the biggest advantages. Banks take 30–60 days to close. Private lenders can fund in 7–14 days. That speed wins deals in competitive markets.
Typical Private Money Loan Terms
- Loan-to-Value (LTV): 65–80%
- Interest Rates: 8–12% annually
- Loan Term: 6–24 months
- Points: 1–3 origination points
- Repayment: Interest-only with balloon payment
Is Private Money Lending Legal?
Yes. Private money lending is legal in all 50 states. However, there are regulations around how many loans a private lender can make before they’re required to obtain a lending license. Always consult a real estate attorney.
Getting Started with Private Money Lending Basics
Whether you’re the borrower or the lender, start by educating yourself on deal structures, legal requirements, and how to evaluate properties. The rest of this blog series breaks each topic down in detail.
CTA: Ready to learn more? Explore our full guide on how to find private money lenders and how to structure a private money deal.
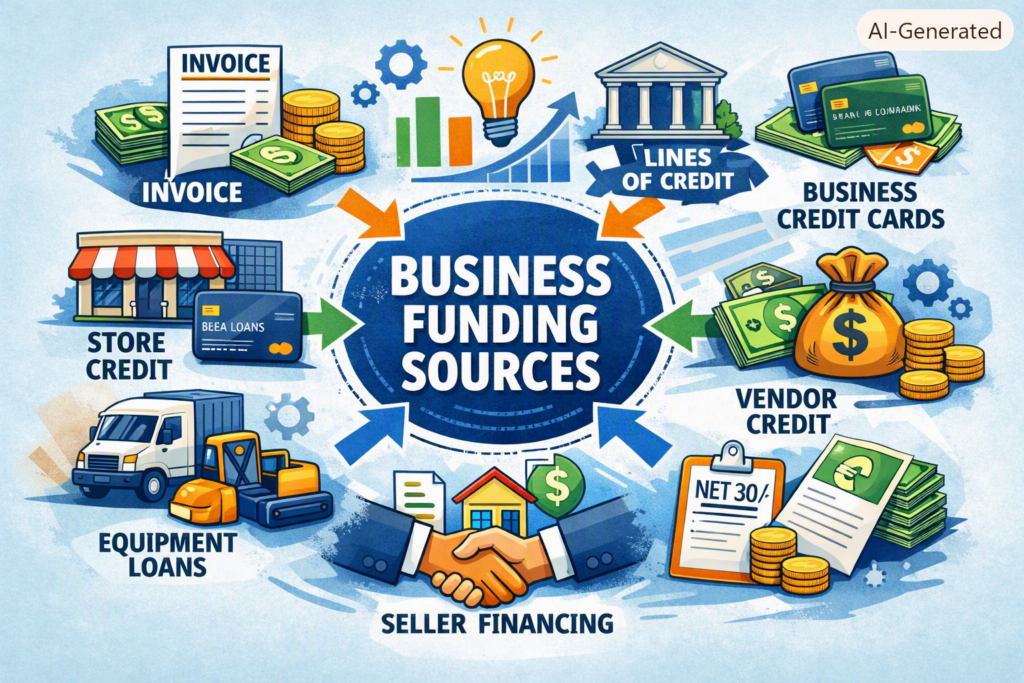
The 7 Funding Sources Every Small Business Can Access in Under 90 Days
 Most people think business funding is some mysterious process reserved for big companies. It isn’t. It’s a sequence.
When your business is structured cleanly, visible in the right databases, and shows basic activity, you unlock the same funding sources everyone else uses — without begging banks or hoping for luck.
Understanding the main business funding sources available early helps small businesses grow predictably.
Here are the 7 funding sources almost every small business can access within 90 days of proper setup.
I also explain how business credit works in my Business Credit Setup post.
1. Vendor Credit (Net‑30 / Net‑60 Accounts)
This is the first rung of the ladder.
Vendor accounts do three things:
- Establish your business credit profile
- Generate your first business credit scores
- Show lenders your business can handle obligations
You only need 3–5 reporting vendors to activate your profile.
This is the “signal layer” that tells lenders you exist.
2. Store Credit (Revolving Accounts)
Once vendors report, you unlock store cards like:
- Office supply stores
- Hardware stores
- Retail business accounts
These accounts:
- Increase your total available credit
- Improve utilization
- Show lenders you can manage revolving credit
This is the “momentum layer.”
3. Business Credit Cards (Unsecured Revolving)
This is where real funding begins.
With:
- Clean entity structure
- Good personal credit
- Active business credit profile
You can access:
- Business Visa
- Business Mastercard
- Business Amex
These cards often come with:
- Higher limits
- Better terms
- More flexible usage
This is the “leverage layer.”
4. Bank Lines of Credit
Once your business shows:
- Revenue
- Clean banking history
- Active credit profile
You can access:
- Unsecured lines
- Secured lines
- Hybrid lines
These are the tools businesses use for:
- Cashflow smoothing
- Inventory
- Expansion
This is the “stability layer.”
5. Equipment Financing
If your business needs equipment, lenders will fund:
- Vehicles
- Machinery
- Tools
- Tech
Equipment financing is easier to get because the equipment itself is collateral.
This is the “asset-backed layer.”
6. Invoice / Receivables Funding
If your business invoices clients, you can turn those invoices into:
- Immediate cash
- Short-term advances
- Working capital
This is one of the fastest forms of business funding because lenders use your receivables as collateral.
This is the “cashflow layer.”
7. SBA‑Backed Funding
This is the top of the staircase.
SBA loans require:
- Clean structure
- Clean credit
- Clean banking
- Clean documentation
But once you reach this tier, you unlock:
- Large lines
- Large loans
- Long terms
- Low rates
This is the “scaling layer.”
The Takeaway
Business funding isn’t about hacks or tricks. It’s about sequence.
When you build your business credit mechanically:
- Vendors activate your profile
- Store cards build momentum
- Business cards create leverage
- Bank lines create stability
- Equipment financing adds assets
- Receivables funding adds cashflow
- SBA unlocks scale
Do the steps → funding becomes predictable.
How I Make Money With Credit and Turn It Into a Legitimate, Lender‑Friendly Business
 When I first heard that you could make money with credit, I was immediately hooked. I read books, watched videos, and scrolled through countless forums to learn everything I could about building personal credit and business credit.
I know how to get high scores and I know how to get credit. What I didn’t have was a legitimate business with a clear plan—something that turns knowledge into profit and qualifies for real funding.
How I Make Money With Credit
I discovered options trading and learned how to sell options for income. But turning that into a business recognized by the IRS is extremely difficult. Banks consider trading risky, so getting funded for that purpose is unlikely.
That’s when I realized something important: turning experience and knowledge into internet content *is* a business. It’s legitimate, fundable, and lender-friendly.
I use AI to help me create content about credit. I monetize that content with Adsense so I earn money when visitors click on ads. I also use AI to help me choose the right NAICS codes, avoid high-risk industries, and stay out of the danger zone with lenders.
My trading strategy doesn’t require much time. That gives me room to report on what’s working, what’s profitable, and how I’m growing my credit limits. I share how I organize my finances, how I manage my trades, and how I build my business credit.
Building Business Credit the Right Way
All of this drives me to create. It helps me, and it helps others. When gurus say they “do it to help people,” I think this is what they mean.
Whether or not my digital marketing business succeeds isn’t the point. What matters is that it pays for what I’m really interested in: the credit.
I sell cash-secured puts using the wheel strategy, and it’s working well for me. Writing blog posts, making Pinterest pins, and posting about credit gives legitimacy to everything I’m doing. That legitimacy helps me get more credit, sell more puts, handle wins and losses, and report on it all with useful content that earns Adsense income and grows my investment accounts faster.
My main job is simple: sell cash-secured puts and manage the results at option expiration.
This newsletter and blog exist to talk about building personal credit and leveraging it into business credit. Business credit offers much higher limits, which allows you to grow exponentially.
Right now, I’m mostly building for SEO. That will help with Adsense income too. It’s all connected.
Once traffic and income start growing, I’ll expand the email newsletter and build more momentum.
It’s all a work in progress, and that progress becomes the content. People want to know what you’re trying, whether it worked, what you changed, and what improved.
A digital marketing or consulting business is exactly what lenders like. Reporting on this journey makes it legitimate. Finally, all the pieces are lining up, and I’m making real progress.
You can also read more in my Credit Optimization section: https://gilberthernandez.com/category/credit-optimization/